
Indian Rupee declines further, RBI's policy awaited
- The Indian Rupee weakens further against the US Dollar due to multiple headwinds.
- FIIs are trimming their stake in Indian stock markets due to higher bond yields.
- Analysts at MUFG expects the RBI to leave its Repo Rate steady on Wednesday.
The Indian Rupee (INR) trades lower against the US Dollar (USD) on Tuesday due to the continuous surge in global bond yields. The USD/INR pair rises to near 96.43, the highest level seen in over two months.
As of writing, 10-year United States (US) Treasury Yields are up 0.24% to near 5.32. On Monday, US bond yields posted a fresh two-decade high near 5.35%. Generally, higher bond yields lead to a risk-off environment, a scenario that diminishes the appeal of riskier assets, such as the Indian Rupee.
Apart from rallying bond yields, the continuous outflow of foreign funds from the Indian stock market is also weighing on the Indian currency.
In the first two trading days of October, Foreign Institutional Investors (FIIs) have offloaded their stake worth Rs. 14,183.36 crore.
What has strengthened US bond yields?
Yields on US-backed securities are rallying significantly for months. Fears of persistent global inflationary pressures due to energy supply shocks induced by the Middle East war are supporting the rally.
The advance in the US Treasury Yields seems not taking a pause even as soft United States (US) Nonfarm Payrolls (NFP) data for September has forced traders to scale back hawkish Federal Reserve (Fed) interest rate expectations.
According to analysts at Societe Generale, though the softer US payrolls report has reinforced the recent pullback in expectations for near‑term Fed tightening, the bank stresses that it is “not a game changer for the hawkish predisposition of the Fed – inflation is the bogeyman.” In their view, the latest jobs print instead “justifies caution over cadence and quantity of future policy adjustments.
RBI’s policy announcement awaited
Going forward, the major trigger for the Indian Rupee will be the Reserve Bank of India’s (RBI) monetary policy announcement.
Analysts at MUFG/BTMU reiterate that they are “officially forecasting RBI to keep rates on hold,” but emphasize that “more importantly we have already been calling for the central bank to start its hiking cycle from December so ultimately we think it’s just a matter of time before policy rates move higher.” They “see a good chance RBI will also move its stance away from neutral to signal a tightening bias,” underscoring a shift in the policy signal even if the near-term decision is unchanged.
In terms of the projected magnitude, MUFG/BTMU note that “we have 50bps of rate hikes in our forecast profile, and have mentioned that there could be a risk of 75bps in total this cycle,” pointing to a backdrop where “growth is strong, liquidity is abundant, credit growth is picking up, fiscal policy is supportive, while higher commodity prices and adverse weather conditions lend inflation risk to the upside in India.” They add that “we are forecasting RBI to hike rates by 50bps this cycle with some risk of 75bps, although we note pricing in the rates market is quite rich already,” suggesting that markets may already be pricing in a relatively aggressive tightening path.
Technical Analysis: USD/INR aims to revisit all-time high near 97.00
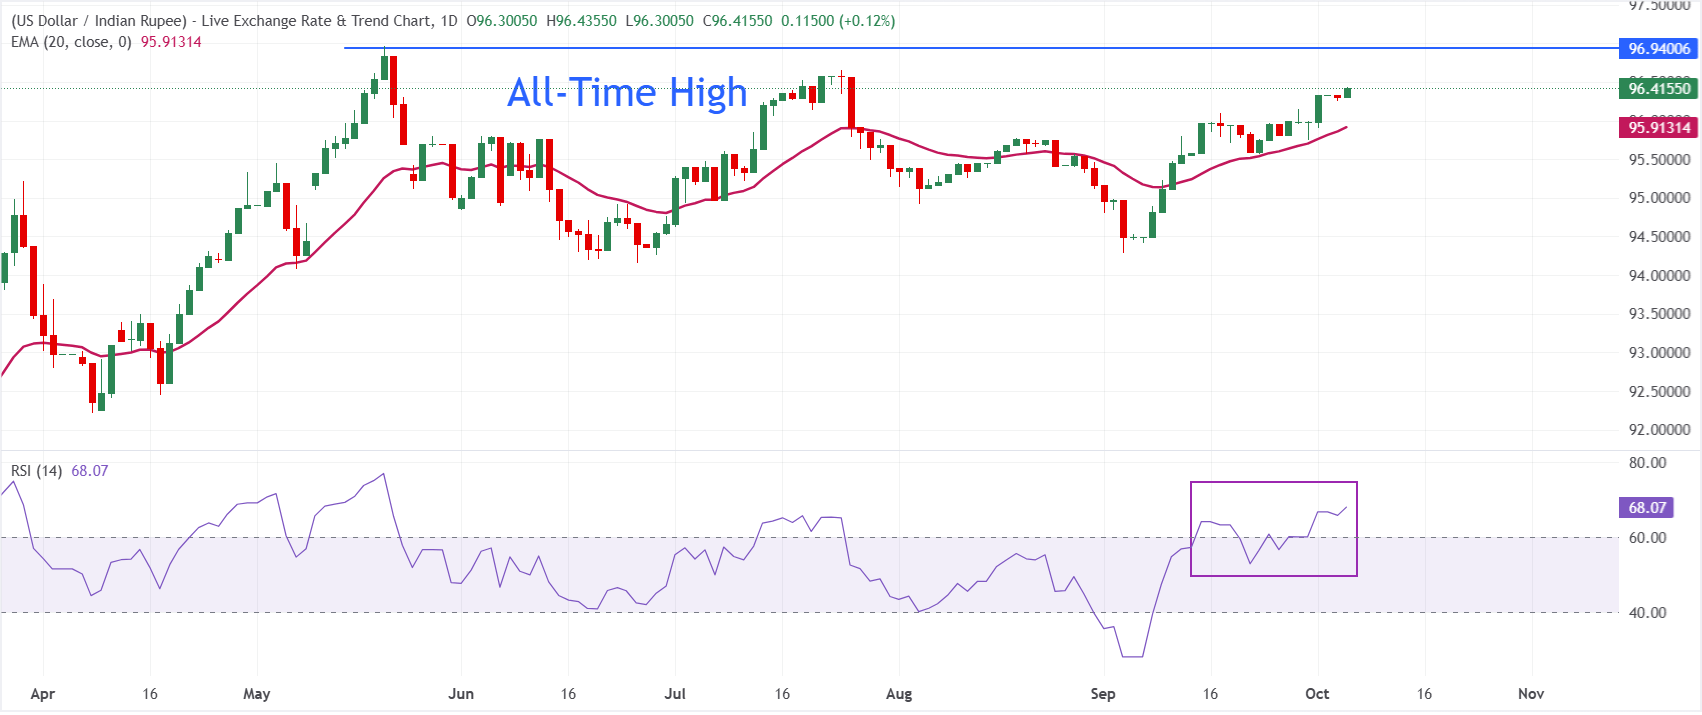
In the daily chart, USD/INR trades at 96.42, extending its advance above the 20-period exponential moving average (EMA) at 95.91 and keeping a near-term bullish bias intact. The pair is supported by this rising EMA, while the Relative Strength Index (14) at 68.07 hovers just under overbought territory, suggesting strong but increasingly stretched upside momentum.
On the downside, initial support is seen at the 20-period EMA around 95.91, where a pullback could attract fresh buying interest as long as the level holds. With no nearby technical resistance levels from the current dataset, further gains would likely be driven by momentum until new highs begin to establish fresh topside reference points.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.